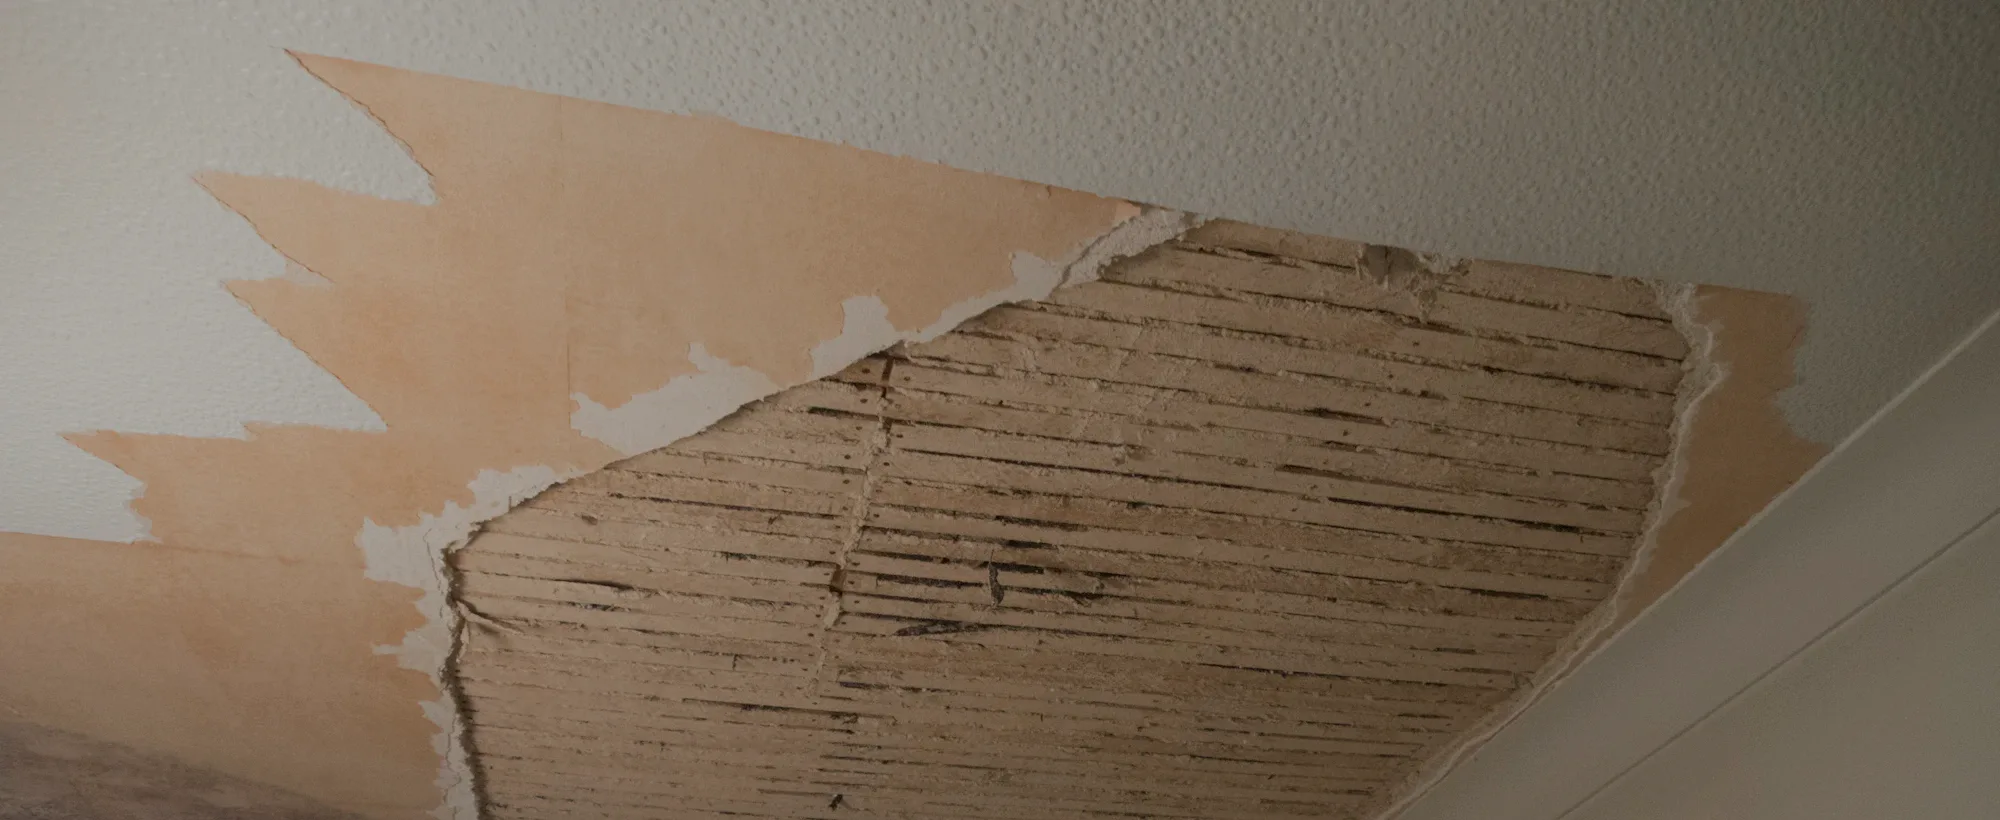
Water damage & insurance rebuilds · San Diego County
A burst pipe is a paperwork problem before it is a construction problem.
When your property suffers water damage, navigating the insurance claim shouldn’t be a second crisis. San Diego Coastal Builder cleanly steps in after the initial emergency drying phase is complete. We document the structural damage, write the exact repair scope your carrier requires, and handle the full reconstruction phase.
Where you are right now
Two stages, and you are standing in one of them.
We step in once the emergency drying is done. Pick the one that matches where your claim actually is.
Owner Dane Ziperski brings five years of specialized experience navigating the structural and bureaucratic lifecycle of an insurance claim.
- Claim engineering
- Writing precise, line-item Xactimate estimates, the exact software carriers demand, so your scope moves without costly delays.
- Structural rebuild
- Hand-selecting premier trade partners to rebuild your custom kitchens, custom bathrooms, and living spaces to pristine condition.
What to expect: while we handle the documentation and scope coordination, standard carrier approval typically takes one to four weeks before physical construction begins.
The step that decides the outcome
Homeowners tend to think the insurance company automatically determines what a repair is actually worth. In practice, the carrier only responds to a document, and that document either describes the loss completely, or it does not.
Let us be completely direct: an insurance adjuster’s job is to adjust down, not up. Left to their own devices, carriers routinely undercut homeowners on reconstruction scopes to save corporate dollars. They drop line items, miss hidden damage, and squeeze structural budgets.
Dane has spent five years working directly with insurance claims, mastering the exact line-by-line Xactimate software the carriers use. We do not wait around for an adjuster to hand over a minimized bid. We engineer an undeniable, fully documented structural repair scope first, ensuring your home gets every dollar required to be rebuilt safely, legally, and to pristine condition.
- Dane has written
- Hundreds of these scopes
- We maximize
- Your insurance settlement
Seamless hand-off. Zero information loss.
Once the carrier approves the claim, the physical reconstruction begins. The biggest point of failure with large restoration companies is the disconnect between the office and the field. Here, your project is run by the exact same person who documented the original damage and engineered the scope: Dane Ziperski. Because the author of the scope is the one managing the trade partners, absolutely nothing gets lost in translation. Your design selections, hidden structural repairs, and specialized milestones are executed exactly as promised.
- Approval
- Usually one to four weeks from submission
- Then
- Into active construction immediately after sign-off
Why this page is different from the others
This is the work Dane came out of, not the work he is moving into.
- Years
- 5Water mitigation first, then running the insurance-funded rebuild side
- Reviews
- 6 of 8Describe a leak, a flood, or an open claim: a fair picture of the work
- Weeks, at most
- 4Typical carrier approval window from submission, often faster
- Claims scoped
- 300+Line-item repair scopes written for carriers, in the software they use
Reviews for Dane at Honor Construction
What homeowners said after their own water loss.
These reviews were left for Dane Ziperski on Honor Construction’s Yelp page, where he ran these projects as senior project manager. They are not reviews of San Diego Coastal Builder, which he founded in 2026 after earning his own general contractor license.
- Two bathrooms rebuilt after a leak
“We had a leak in our house and Dane and his contractor Adrian got referred to us to help us rebuild our bathrooms. …”
Kevin H.ElitePacific Beach, San Diego, CA · April 2026
Yelp review for Dane at Honor Construction
Why the scope matters most
The document decides the outcome.
Homeowners tend to think the carrier decides what your repair is worth. In practice, the carrier responds to a document: a scope of repairs that either describes the loss completely or does not.
Dane wrote hundreds of them. He knows what a carrier needs to see, what gets flagged, and how an incomplete scope turns into a homeowner paying out of pocket for something that should have been covered.
Approval usually lands one to four weeks after submission. The single biggest factor in that timeline is how thoroughly the damage was documented on day one.
Maximizing your claim: the power of an expert scope
Insurance carriers do not pay out based on what you deserve. They pay out based on what is explicitly proven in writing. Because an adjuster’s structural goal is to minimize corporate payout, their initial estimate will almost always miss the hidden realities of a premium reconstruction.
That is where my background completely changes the math for you. I do not guess at numbers or wait around for a minimized insurance settlement. I leverage five years of fighting for homeowners inside the insurance system to build an airtight, bulletproof recovery plan.
Speaking their language
I write your repair scope using Xactimate, the exact same line-item estimating software that your carrier uses. Because I know how adjusters look at files, I know how to input the data so it gets approved.
Exposing the hidden damage
Adjusters only scope what is easily visible. I aggressively document the secondary damage they try to ignore: trapped subfloor moisture, structural framing rot, electrical compromise, and code compliance upgrades.
Itemizing total recovery
A generic “kitchen repair” bid gets cut down. I detail every single corner bead, baseboard profile, drywall texturing layer, and plumbing detachment required. When every line item is technically undeniable, the carrier is forced to fund a complete restoration to pre-loss condition, rather than a cheap cosmetic patch.
Your scope is engineered from day one to win. You are not begging an insurance company for a fair number; we are presenting them with a professional data set they cannot legally or structurally ignore.
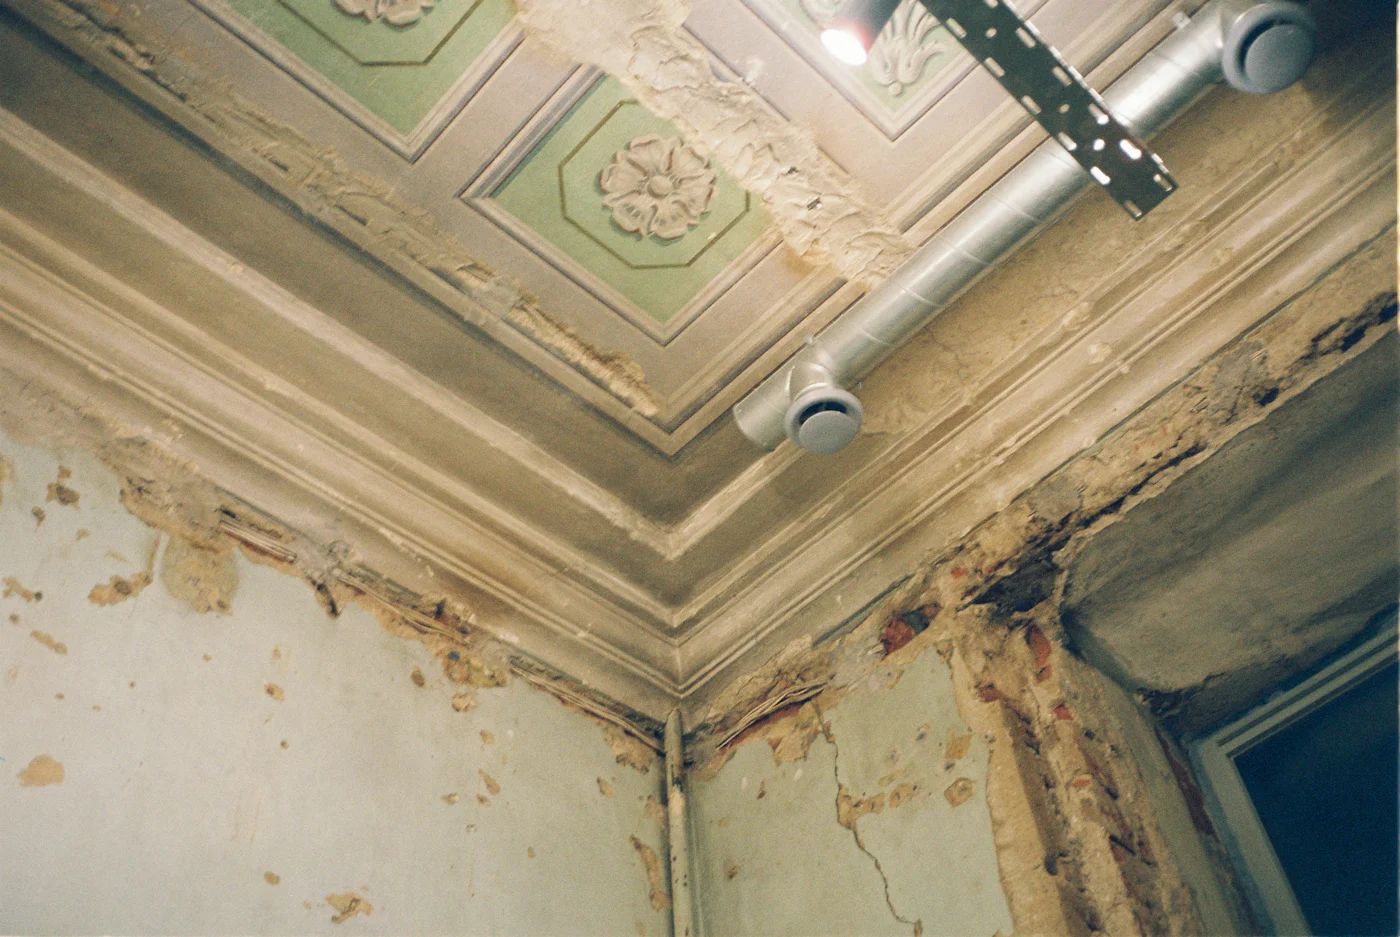
The loss, and the rebuild
What gets documented, and what it turns back into.
Filter to either half. If you are photographing your own loss right now, the first set is a decent guide to what is worth capturing.
How it runs
What the process looks like.
- 1
Step 1: Document and scope
Photos, measurements, and a written repair scope submitted to your carrier. This is the step that decides what gets approved, and it is where experience shows.
- 2
Step 2: Rebuild
Once the claim is approved, the same person who wrote the scope runs the reconstruction. Typically one to four weeks from submission to approval.
Questions
What homeowners ask.
Does homeowners insurance cover water damage repairs?
It depends on the cause of loss and your policy, and that determination is your carrier’s to make, not ours. What we can tell you is how the process runs: the damage gets documented, a repair scope is written and submitted to the carrier, and once it is approved the rebuild starts.
How long does an insurance claim take to get approved?
Typically one to four weeks from the time the scope is submitted. Dane wrote and filed these scopes for five years, and the single biggest factor in that timeline is how completely the damage was documented in the first place.
What actually happens after a pipe bursts?
The sequence is consistent: a plumber stops the leak, a mitigation crew dries the property out and removes wet material, then a general contractor documents the loss, writes the repair scope for the carrier, and rebuilds once it is approved. Dane worked in water mitigation before running the rebuild side, so he has been at both ends of that chain.
When do you get involved after water damage?
Once the emergency drying is done. A plumber stops the leak and a mitigation crew dries the property and removes wet material; San Diego Coastal Builder steps in after that to document the structural damage, write the repair scope your carrier requires, and run the reconstruction once the claim is approved.
What should I photograph after a leak or flood?
Everything wet, before anything is removed: the source of the water, the affected floors, walls, and ceilings, and anything that was damaged. Photos, measurements, and a written repair scope are what get submitted to the carrier, and how completely the loss was documented is the single biggest factor in how quickly it is approved.
Does the person who writes the scope also run the rebuild?
Yes. The biggest point of failure at large restoration companies is the disconnect between the office and the field. Here the project is run by the same person who documented the original damage and wrote the scope, Dane Ziperski, so nothing is lost in a hand-off.
Do you decide whether my claim is covered?
No. Whether a loss is covered is your carrier’s determination, and it depends on the cause of loss and your policy. San Diego Coastal Builder does not negotiate claims, does not determine coverage, and does not promise approval amounts. What it does is document the damage thoroughly, write an accurate line-item repair scope in the software carriers use, and answer the carrier’s questions about it.
Have an open claim?
Tell us what happened and where the claim stands. Even if you are not ready to hire anyone, you will get a clear picture of what should happen next.